
Set a target from a price range you can afford, then save toward it on a schedule. The Consumer Financial Protection Bureau says most buyers need at least 3% of the home price down, many loans require 5% or more, and closing costs typically add 2% to 5%. The sinking fund method in ProfitDrawer's zero-based budget guide works here too: divide the amount you need by the months until you plan to buy.
Steps, using CFPB guidance:
- Pick a price range and work out the down payment and closing costs for it. The CFPB says you can often save money by putting down at least 10%, and save the most at 20% or more.
- Keep an emergency fund separate. The CFPB's rule of thumb is at least three to six months' worth of expenses, and it subtracts this, other savings goals, moving costs and renovation money from your cash before working out your maximum down payment.
- Divide the target by the months until you want to buy, and add that amount as a monthly budget line.
- Save it on payday, before flexible spending, and track progress monthly.
- Ask about help. The CFPB says a housing counselor may know local assistance programs; VA loans generally need no down payment for eligible servicemembers and families, and USDA has a program for eligible rural households.
- Gifts from family can count for some loans if you can show where the money came from.
The CFPB says to think twice before using retirement savings, and notes low down payment options usually cost more over time. General information, not financial advice.
Source: Determine your down payment (Consumer Financial Protection Bureau) · Updated
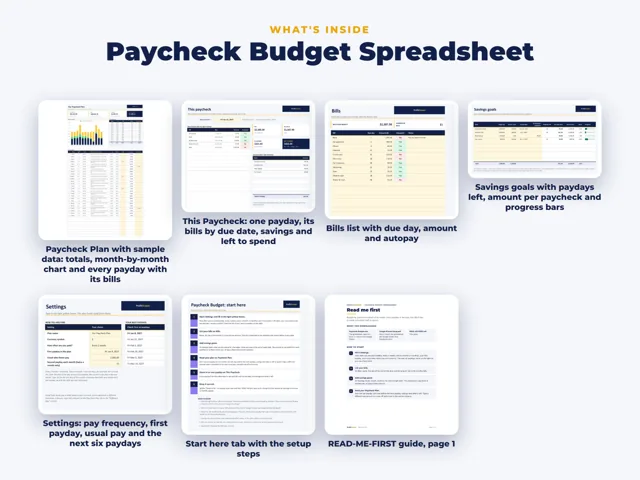
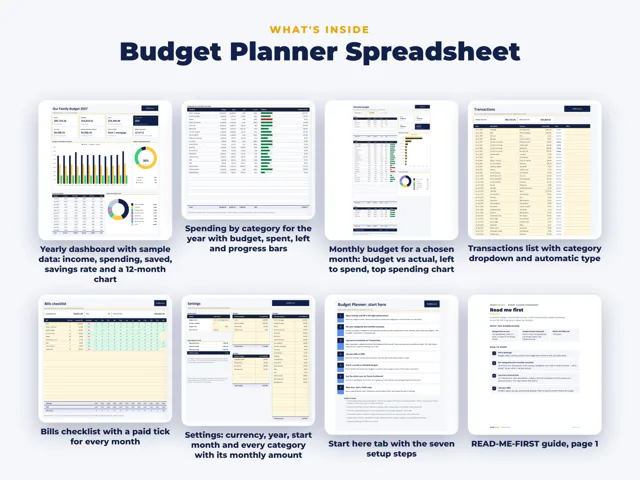
Tools and spreadsheets for this
Related questions
All questions on ProfitDrawer Answers →
General information, not tax, legal or financial advice. Check the rules for your state and your situation.