
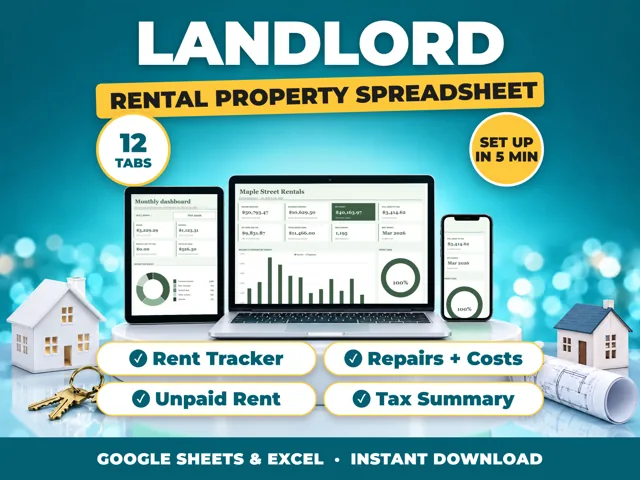
Record each rent payment, fee and kept deposit as income, and each mortgage interest, tax, insurance, repair and management cost as an expense, by property and month, with receipts. Rental income and expenses go on Schedule E (Form 1040). IRS Publication 527 (2025) says advance rent is income in the year you receive it, and improvements must be capitalized and depreciated, not deducted at once. A ProfitDrawer landlord spreadsheet has these categories set up.
Income to record:
- Rent, including advance rent, in the year received
- Late fees and pet fees
- Security deposit amounts you keep (a deposit you plan to return is generally not income)
- Lease cancellation payments
- Expenses a tenant pays for you
Expenses to record:
- Mortgage interest and property tax
- Insurance, utilities you pay, HOA fees
- Repairs and maintenance, cleaning, supplies
- Property management, advertising, legal and professional fees
- Travel to the property: for the 2025 tax year, the standard mileage rate is 70 cents a mile
Repairs vs improvements. A repair keeps the property in working order and is deducted. An improvement, such as a new roof, is capitalized and depreciated. Publication 527 advises records that keep the two apart.
Tips: use one bank account for the rentals, note the property on each entry if you own more than one, and keep closing documents for the depreciation basis. General information, not tax advice.
Source: IRS Publication 527 (2025): Residential Rental Property · Updated
Tools and spreadsheets for this
Related questions
- Is there a ProfitDrawer spreadsheet for landlords?
- What is the IRS standard mileage rate for business in 2026?
- What business expenses are tax deductible?
- How long should a small business keep tax records and receipts?
- Do I need a separate bank account for my small business?
- How do I keep track of business expenses as a small business owner?
All questions on ProfitDrawer Answers →
General information, not tax, legal or financial advice. Check the rules for your state and your situation.