
Yes, within limits. Under current IRS rules you can elect to deduct up to $5,000 of business start-up costs in the year your business begins, reduced by any amount your start-up costs exceed $50,000. The rest is amortized over 180 months, starting with the month you begin operations. These rules apply to 2025 and 2026 returns. ProfitDrawer's free startup cost calculator adds up one-time and monthly costs before you open.
Start-up costs are expenses you incur before you actually begin business operations, such as advertising, travel, surveys and training (IRS Publication 583). A separate deduction of up to $5,000 applies to organizational costs, with the same $50,000 reduction.
Example (example numbers only): $8,000 of start-up costs. You deduct $5,000 in the first year. The other $3,000 is spread over 180 months, about $16.67 a month, or $200 for each full year.
Points to know (Form 4562 instructions, 2025):
- You make the election by deducting the costs for the year your business begins. No statement is required, and once made, the election cannot be revoked.
- At $55,000 or more of start-up costs, the $5,000 first-year amount is reduced to $0 and everything is amortized.
- Assets such as machinery or office equipment are usually recovered through depreciation, not as start-up costs.
- Amortization is reported on Form 4562.
Keep receipts from before your opening day with your business records. General information, not tax advice.
Source: IRS Publication 583, Starting a Business and Keeping Records · Updated
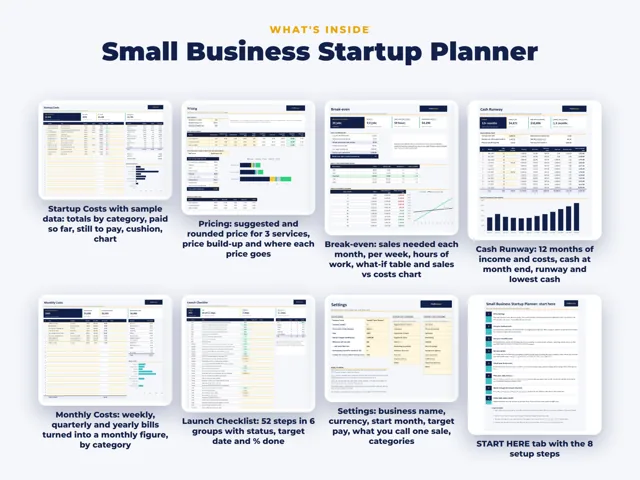
Tools and spreadsheets for this
Related questions
All questions on ProfitDrawer Answers →
General information, not tax, legal or financial advice. Check the rules for your state and your situation.